
Author: Robbie Petersen, Investment Partner at a16z crypto
Compiled by: Gu Yu, ChainCatcher
For most of financial history, the bottleneck was the supply of new markets, not demand. Blockchains remove that bottleneck. I believe this will unleash an explosion of net-new markets.
Markets are mechanisms for transferring risk. Every trade is nothing more than two counterparties agreeing to transfer some exposure at an agreed price. Abstractly, risk can be expressed along two independent axes:
Underlying unit: the underlying exposure (e.g., a company's cash flows, a barrel of oil, an election outcome, a borrower's credit, a GPU hour)
Instrument: the mechanism for transferring that exposure (e.g., spot, futures with an expiry, perps, options, event contracts)
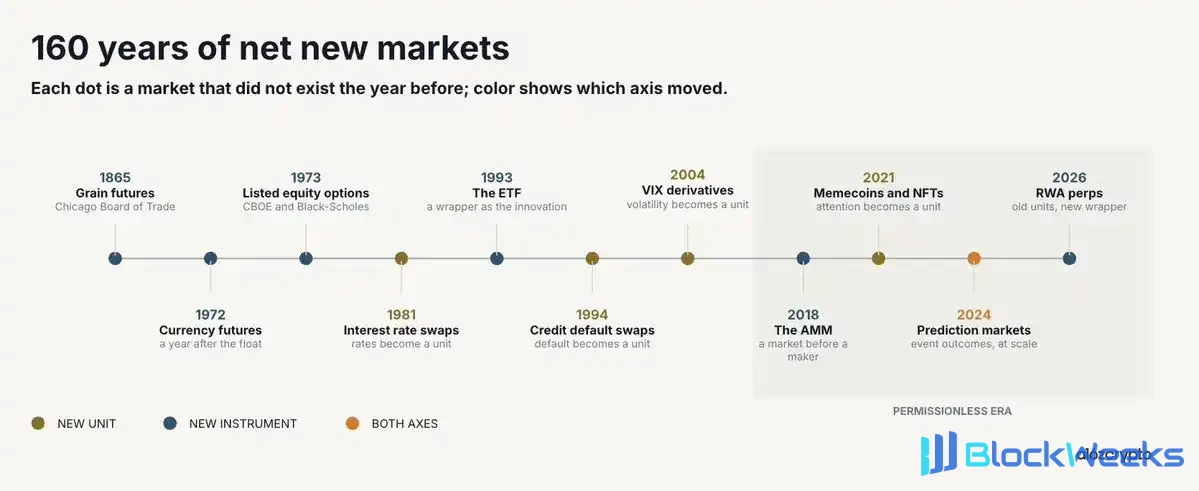
Almost the entire history of finance is a story of slow innovation along only one axis. Spot grain markets existed for thousands of years before Chicago listed grain futures in 1865. Currencies began floating in 1971 and had futures in 1972. Equity options existed as customized dealer contracts for centuries before becoming a listed market in 1973 with the CBOE and Black-Scholes. ETFs did not appear until 1993.
New risk units are even rarer. Interest rates did not become broadly tradable until 1981. Default risk waited until credit default swaps in 1994 for an instrument. Volatility waited until VIX derivatives in 2004. Event outcomes only became a real market in recent years through prediction markets.
Demand for these markets was arguably never the problem. Farmers wanted to hedge their harvest long before the CBOT existed. Creditors wanted to transfer default risk long before CDS existed. Instead, what slowed growth was the supply of these markets. And historically, two things constrained supply:
1. Listing committees and legal frameworks
2. Geographic fragmentation
Blockchains eliminate both. They make issuance permissionless and distribution global. In my view, this is the killer use case in its purest form: blockchain is the first technology that lets market supply catch up with potential global demand.
This thesis is also borne out empirically. Almost every category-defining outcome in crypto is downstream of this killer use case. From perps and spot DEXs, to prediction markets, lending markets, and then memecoins, NFTs, and tokenized real-world assets, value has flowed to those who have net-new market issuance rights and/or trading venues on-chain.
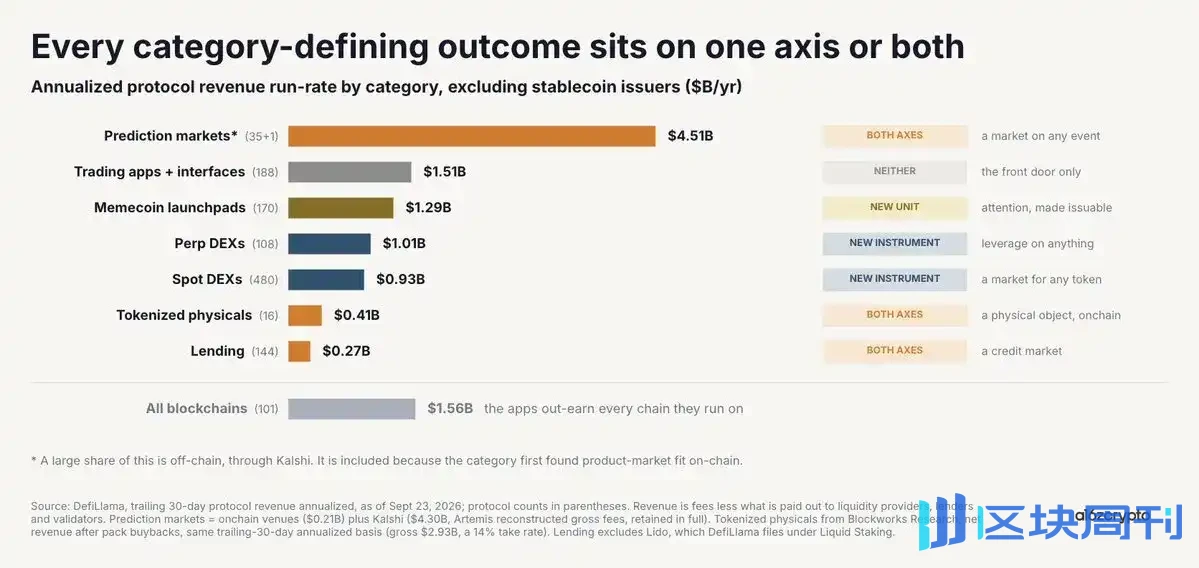
Each of these respective categories either permissionlessly created a net-new risk unit or created a new way to transfer that risk.
On the unit side, crypto engineered exposures that previously had little or no financial expression. Prediction markets, although they can be traced back to the Iowa Electronic Markets, found product-market fit on-chain, expanding nonlinearly and turning discrete events—an election, a Fed decision, a court ruling—into tradable units. Peer-to-peer lending markets turned individual credit relationships into something with real-time continuous pricing. Pre-IPO markets turned exposure that was originally available only to a handful of secondary brokers into something users can trade and hold at scale. Even memecoins and NFTs turned abstract risk units like attention flows and cultural relevance into clear and tradable markets.
In addition, crypto has likewise either created—or scaled—new mechanisms for transferring these risk units. AMMs let markets exist before a market maker agrees to quote. Perps, first proposed in 1993, found product-market fit on-chain by collapsing dated, fragmented exposure into a single contract balanced by funding rates. Binary contracts turned event outcomes into tradable markets worth $1 or zero. Pool-to-pool lending replaced bilateral loans with shared pools and utilization curves. Bonding curves fused issuance and price discovery, so an asset has a market from the first buyer.
Perps are the proof
Nothing expresses this thesis more cleanly than perpetual futures, and nothing proves it more cleanly than the recent rise in on-chain non-crypto trading volume.
Because perps are synthetic, the listing constraint collapses into two things: a robust oracle, and two counterparties willing to take the other side. With those two things, almost anything can have a leveraged market. In this sense, perps are one of the most effective coordination mechanisms ever created.
By the same logic, Hyperliquid is the closest thing we currently have to a global financial coordination platform. HIP-3 and HIP-4 let users issue their own derivatives, plug into the venue's global front end, and monetize accordingly. Lowering the friction of launching markets means more markets, and demand will naturally select the winners.

It is no coincidence that one of the fastest-growing markets in crypto—and increasingly across finance as a whole—is issued permissionlessly onchain and distributed globally. In July of this year, onchain RWA perps trading volume reached an annualized run rate of $1.4 trillion, accounting for half of the Hyperliquid order book. Abstractly, this is simply existing risk units—stocks, oil, storage stocks—meeting a new transfer tool without permission. Downstream, this recombination has spawned an explosion in trading volume.
Note also that each quarter, some net-new market dominates. Q4 2025 was US equities and commodities; the first half of 2026 was oil, natural gas, and metals, and most recently semiconductors and storage stocks. This again reflects the core thesis. The supply of net-new markets is now catching up to whatever the world wants to trade in that quarter.

Yet the deeper downstream implication is that permissionless and 24/7 trading have become the wedge for price discovery to become authoritative onchain. During the oil shock in February of this year, when CME was closed, WTI found price discovery on trade.xyz, becoming one of the most liquid markets globally. Likewise, we saw the Cerebras and SpaceX Pre-IPO stock markets price IPOs more accurately than bankers, with only a marginal difference between the last hour of the Pre-IPO perp and the actual opening price.
The market is increasingly making clear that the structural constraints of traditional markets—lack of 24/7 trading, geographic barriers, lack of Pre-IPO access, margin silos—are the sustainable wedge for onchain markets.
Looking Ahead
What markets transfer is risk units. Arguably, for most of financial history, markets have been constrained by geography, listing committees, and legal frameworks. Today, these constraints no longer exist. The reach of onchain markets is no longer limited to the existing set of assets, but to any risk that anyone—or any institution—anywhere wants to trade.
This means we will continue to see explosive growth of new onchain markets. This includes both new ways to transfer old risks: commodity and FX futures, indices, round-the-clock equity exposure; and new risk units themselves: compute futures, macro-indicator-based (such as CPI), music, social trends, sports, and any other underlying asset that can be oracle-predicted and traded bilaterally. And the applications and protocols that create these markets, as well as the venues that trade them, are where value can truly be captured.





