Author: tranks (@heytranks, data provided by Bonanza Lab)
Compiled by: Shenchao TechFlow
Shenchao Introduction: As one of the global hubs with the most active retail crypto trading, the listing trends of South Korea's Korean won (KRW) trading market have historically had a significant liquidity spillover effect on global secondary markets. However, since the implementation of the Act on Reporting and Use of Specific Financial Transaction Information in 2021 and the formation of the Digital Asset Exchange Alliance (DAXA) by the five major exchanges, the listing standards of the Korean market are undergoing profound institutional changes.
Detailed statistics by on-chain data think tank Bonanza Lab on Upbit, Bithumb, Coinone, Korbit, and Gopax show that the proportion of Korea-only listings of altcoins plummeted from 85% to single digits after regulation took effect, while assets with more than two years of mature trading history on mainstream overseas exchanges have become the focus of review. Although this regulatory evolution has significantly reduced investment warning and delisting risks, it has also weakened the trading fee revenue brought by first-day surges, forcing Korean exchanges to explore the endgame of business transformation.
Regulatory framework gradually takes shape, share of Korea-only listings drops significantly
As South Korea's crypto regulatory framework has been gradually established and improved, the proportion of pure Korea-only listings has fallen sharply.
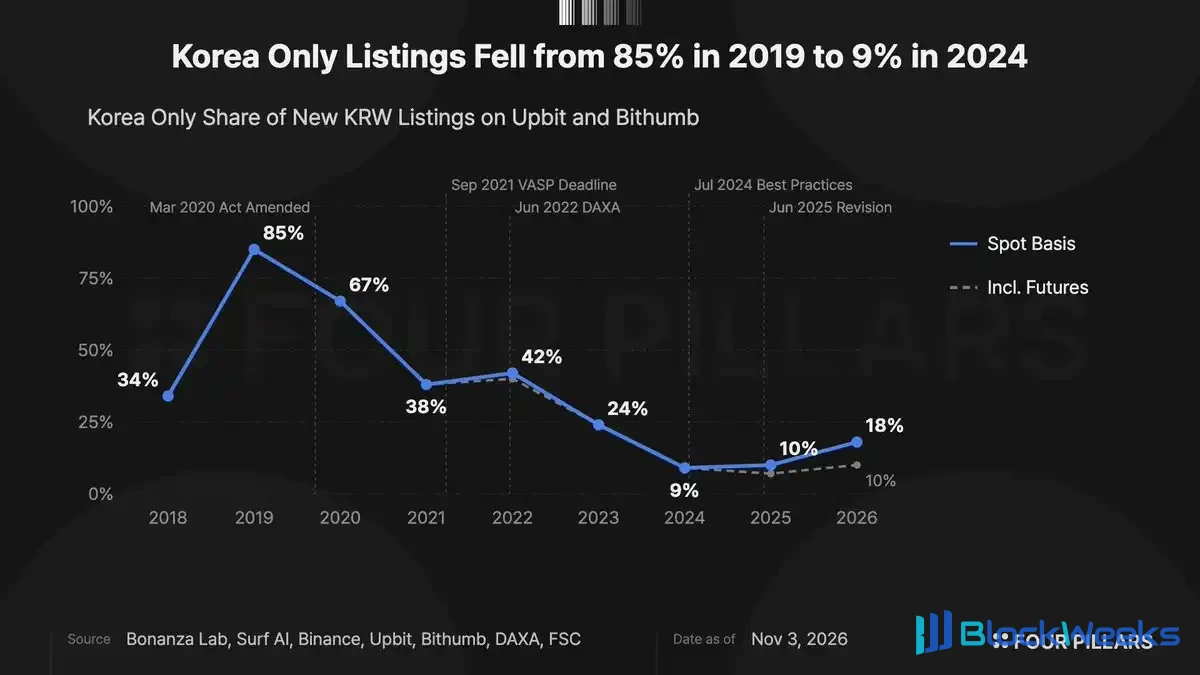
Chart: Trend in the share of Korea-only listings among the five major Korean won exchanges (2019 to 2026)
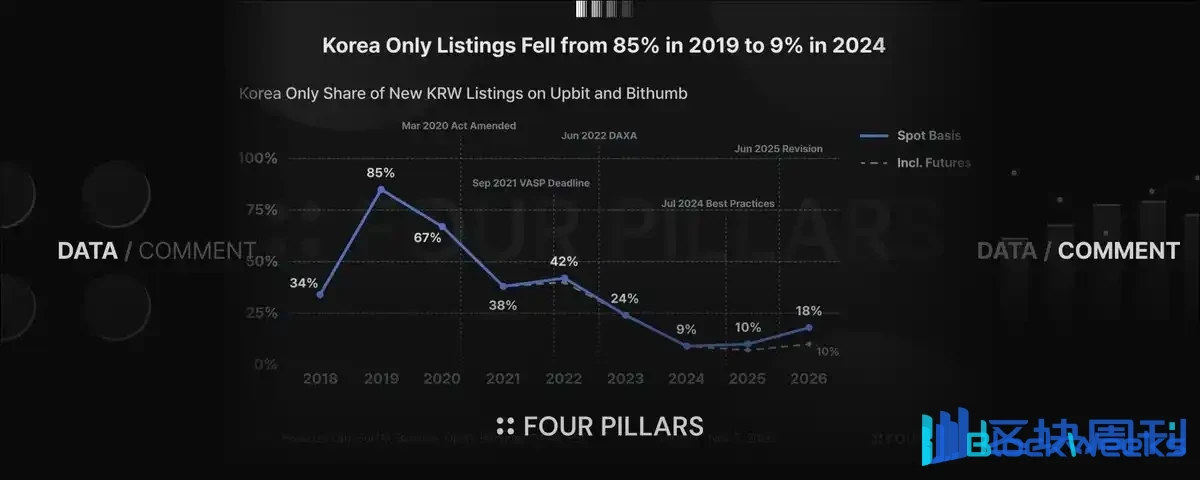
The chart above shows the evolution of the share of pure Korea-only assets among newly added Korean won trading pairs on the five regulated Korean won (KRW) trading platforms: Upbit, Bithumb, Coinone, Korbit, and Gopax.
This proportion fell significantly from 85% in 2019 to 9% in 2024. Comparing this with the development milestones of South Korea's virtual asset regulation, the institutional evolution path is very clear.
This shift began with the Act on Reporting and Use of Specific Financial Transaction Information (referred to as the Specific Financial Information Act). The act took effect in March 2021 and required trading platforms to complete official real-name declaration registration by September 2021.
For the Korean won market, obtaining bank real-name verified accounts became a mandatory legal requirement, and exchanges had to strictly implement traditional-finance-level anti-money laundering (AML) compliance standards. It is estimated that these compliance standards directly reshaped exchanges' listing decisions.
In fact, the number of pure Korea-only listings dropped sharply from 19 per quarter to only 3 in the third quarter of 2021 (the quarter of the registration declaration deadline), after which listing targets in the Korean market fully shifted toward assets that already had trading records overseas.
What followed were the listing review standards commonly followed by the exchanges. In 2022, the five Korean won exchanges jointly formed the Digital Asset Exchange Alliance (DAXA) and formulated unified review guidelines, whose listing best practice standards officially took effect in July 2024.
Although the guidelines do not make overseas listing an absolute hard prerequisite, they stipulate that assets traded for more than two years on compliant overseas exchanges can be regarded as automatically meeting basic review requirements such as white papers and information disclosure.
In 2026 (as of October), although the share of pure Korea-only listings rebounded slightly to 18%, if assets that first traded in overseas futures markets are excluded, the actual share remains at a very low level of 10%.
Total listings grow against the trend, timing dynamically adjusted with market cycles
Although the share of pure Korea-only listings has shrunk significantly, this does not mean that the total number of listings on Korean exchanges is decreasing.

Chart: Number of new listings in the Korean won market and distribution of overseas trading time structure
Statistics show that the total number of new listings in the Korean won markets of the two mainstream platforms Upbit and Bithumb increased from 43 in 2022 to 116 in 2023, reached 125 in 2024, and climbed to 238 in 2025.
The length of time an asset traded overseas before entering the Korean market shows a high degree of cyclical correlation with overall market conditions.
In 2025, when Bitcoin was near historical highs in Korean won terms, as many as 111 assets were quickly introduced into the Korean market within 30 days after overseas listing, accounting for 47% of that year's total listings.
In sharp contrast, in 2026, mature assets that had traded overseas for more than one year became the main force of new additions, totaling 52 (31%), and even veteran tokens that had traded overseas for more than six years (such as CRV and RSR) were officially introduced into the Korean market during this period.
Therefore, the listing practices of Korean exchanges have changed significantly: on the one hand, they adhere to the access framework centered on assets already listed overseas established during the regulatory formation period; on the other hand, they flexibly advance or delay specific listing timing according to the temperature of the secondary market.
Post-listing stability improves, default delisting rate of mature overseas assets drops significantly
As the share of assets with an overseas trading base continues to rise, the overall stability of tokens after listing in Korea has also improved significantly.

Chart: Changes in the proportion of assets placed on investment warning or delisted within two years after listing
The proportion of assets placed on the exchanges' "investment warning" list or announced to terminate trading (delisted) within two years after listing steadily declined from 24% for the 2020 listing cohort to 10% for the 2024 cohort.
Assets with different listing attributes show extremely significant divergence in risk performance. Among all assets listed between 2020 and 2024, 44 of the 148 purely domestically first-listed tokens (30%) were placed on warning or delisted within two years; whereas for assets that were first traded overseas, only 26 of 279 (9%) experienced such situations, with a violation warning rate less than one-third that of domestically first-listed tokens.
Overseas incubation time and price resilience: first-month price volatility tends to flatten
At the same time, the length of time an asset has been traded overseas has had a decisive impact on its secondary market price trajectory after listing in South Korea.

Chart: Comparison of median price declines 30 days after listing for assets with different overseas trading histories
From the statistical median, those assets that were urgently introduced to South Korea within 30 days after listing overseas saw a median price decline of as high as 39% within 30 days after listing in South Korea; by contrast, mature assets with more than one year of overseas trading history saw a median price decline of only 7% 30 days after listing.
In short, assets that were first traded overseas have a lower probability of being placed on investment warning or delisted after listing in South Korea; and among these assets, the longer the overseas incubation time, the smaller the price drawdown in the early period after listing in South Korea.
Because the best-practice listing guidelines effectively reduce the review burden for such mature assets, even if listing schedules are dynamically fine-tuned with bull and bear market conditions, the listing focus of South Korean exchanges will most likely remain anchored in the long term on mature assets with long overseas trading histories.
New challenges for exchanges: cooling liquidity and revenue transformation beyond listings
However, a listing model that over-prioritizes overseas trading history is not entirely good news for exchanges.

Chart: First-day trading volume share and exchange fee dependence model
This is because those established assets that have already been fully traded overseas often generate relatively limited speculative trading volume on their first day of listing in South Korea.
Since the vast majority of South Korean exchanges' operating revenue is highly dependent on spot trading fees, newly listed tokens lacking first-day explosive momentum may directly drag down exchanges' profitability.
Of course, if a bull market restarts in the future, the number of listings of emerging popular assets that have just been released overseas may increase again, thereby alleviating revenue pressure in the short term. But if they rely solely on a listing structure that follows the tide, exchanges will find it difficult to build a stable and cycle-resistant sustainable business model.
As the regulatory compliance system matures, the safety and stability of listed assets have indeed improved significantly. The core challenge truly facing South Korean exchanges today is how to develop entirely new trading demand and diversified business revenue sources beyond purely listing-driven growth.
Note: The data and statistical support for this article are provided by on-chain research institution Bonanza Lab (https://bonanzalab.io).