Author: Jae, PANews
On November 3, as the U.S. midterm elections were in full swing, the CFTC's regulatory battlefield also caught fire.
In the morning, the U.S. Commodity Futures Trading Commission (CFTC) approved U.S. equity perpetual futures to enter the U.S. regulated market, and U.S. equity perpetual contracts obtained clear U.S. regulatory permission for the first time. In the afternoon, the opposing gunfire sounded. The Capital Markets Alliance (CMA), backed by traditional institutions such as Cboe Global Markets and Citadel Securities, filed a lawsuit in the U.S. District Court for the Southern District of New York, seeking to vacate the CFTC's product approval.
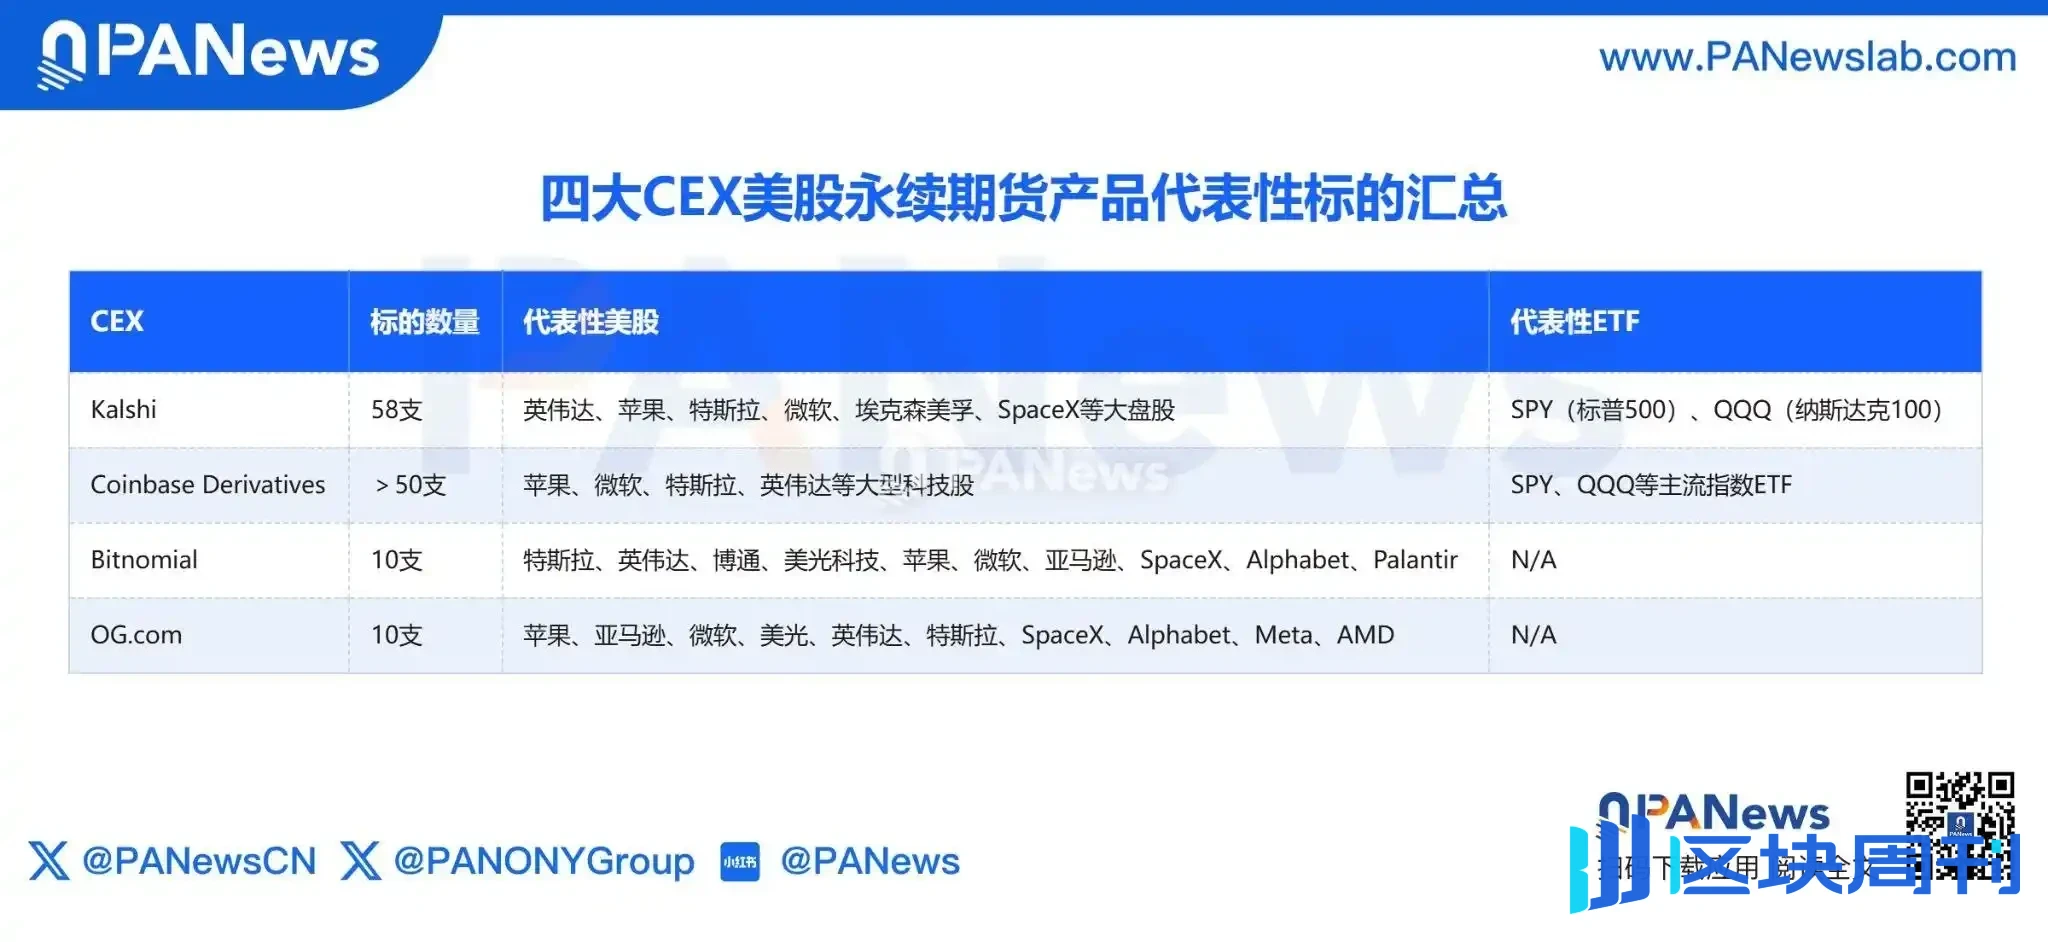
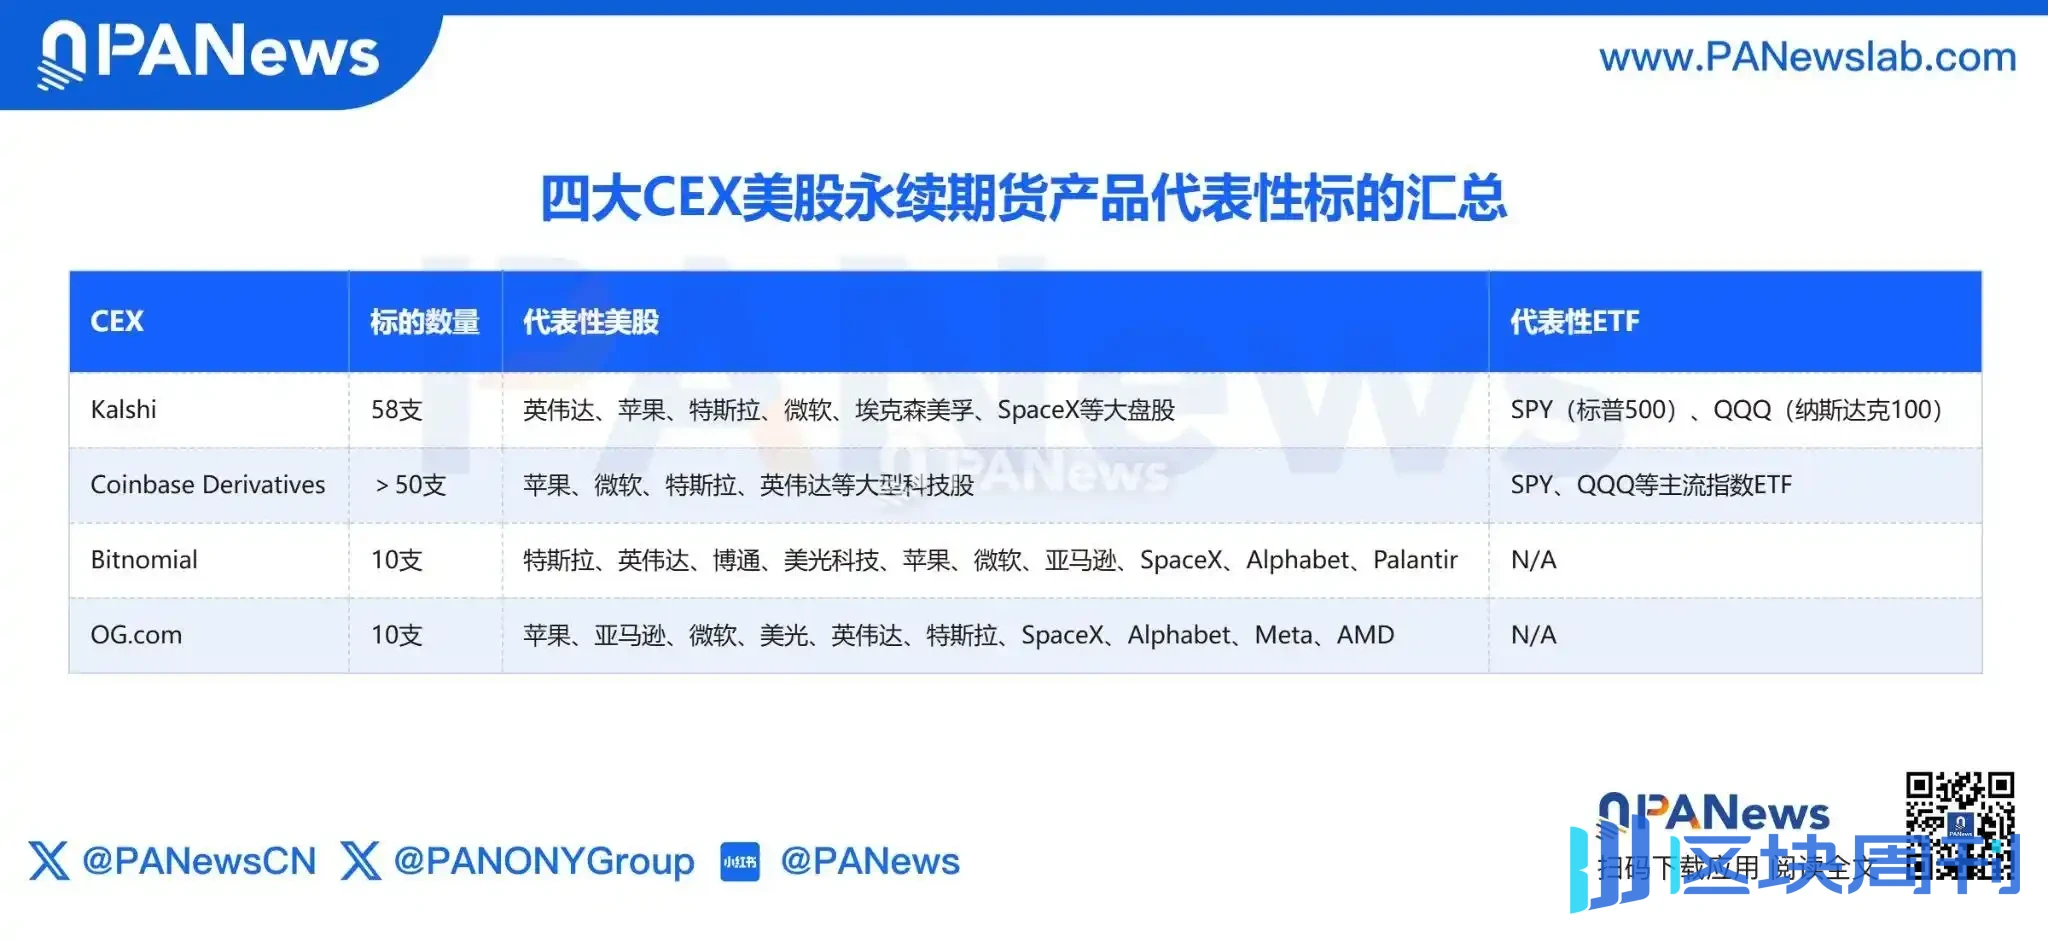
The collision of approval and blocking on the same day is by no means an accidental market episode. Previously, the U.S. equity perpetual futures products of four crypto institutions—Kalshi, Coinbase, Bitnomial (a Kraken sister company), and OG.com (under Crypto.com)—were already on the way. A confrontation between old and new forces is playing out in U.S. equity perpetual contract products.
CFTC Opens the Gate, Four Crypto Exchanges Rush to the Finish Line First
Perpetual contracts have long become the most mainstream trading instrument in the crypto market. They have no fixed expiration date and rely on a funding rate mechanism to anchor the contract price to the spot price. Traders do not need to hold stocks to amplify risk exposure through margin, at the cost of having neither shareholder status nor voting rights.
Now, this trading mechanism is being transplanted to the U.S. equity market. The CFTC's shift did not happen suddenly. On May 29, the CFTC first approved Kalshi's Bitcoin perpetual futures BTCPERP, setting a precedent. Subsequently, the regulator issued a policy statement on the listing of perpetual contracts, proposing that different underlying assets such as equities and precious metals require "case-by-case review."
After that, institutional product applications quickly spread to U.S. equities and ETFs: on September 18, Kalshi, Bitnomial, and Coinbase Derivatives submitted on the same day; on September 24, OG.com followed suit.
The first batch of underlying assets from the four crypto trading platforms was highly consistent, almost all anchored to large-cap tech stocks such as Nvidia, Apple, Tesla, and Microsoft, as well as mainstream index ETFs such as SPY and QQQ. Assets with the best liquidity and the highest retail recognition have always been the first stop for new categories.
From the perspective of trading mechanisms, this batch of U.S. equity perpetual plans to trade continuously from Sunday evening to Friday evening, covering most of the time outside regular U.S. equity hours, but not the crypto market's 24/7. For ordinary investors, the most intuitive change is: in the future, they will not need to rely on traditional U.S. equity options to directly trade the price fluctuations of large tech stocks, making short selling and hedging more flexible.
It is worth noting that the CFTC's approval is more based on the mechanism of "deemed approved upon expiration of the review period," rather than issuing formal approvals or licenses to the four companies one by one. The initial 45-day review period expired on November 2 for the first three, while OG.com will have to wait until November 8.
However, this admission order does not mean that U.S. equity perpetual products are out of the sight of the U.S. Securities and Exchange Commission (SEC). Under the Commodity Futures Modernization Act of 2000, security futures fall within the joint regulatory scope of the CFTC and the SEC. In addition to obtaining the CFTC's Designated Contract Market (DCM) qualification, platforms also need to complete registration with the SEC under the rules for security futures trading venues.
Wall Street Financial Giants Sue the CFTC, U.S. Equity Perpetuals Face a Definitional Battle
The green light is on, but some are not convinced. On the afternoon when the CFTC approved U.S. equity perpetual products, the CMA, backed by Wall Street giants, filed a lawsuit in the U.S. District Court for the Southern District of New York, seeking to vacate the relevant approval.
The core of the CMA's complaint is a definitional question: Are U.S. equity perpetuals considered security futures or security-based swaps?
The CFTC classifies U.S. equity perpetuals as security futures, thereby applying the regulatory framework shared by the CFTC and the SEC. The CMA argues that U.S. equity perpetuals, which have no fixed expiration date and rely on periodic funding payments to maintain price anchoring, are essentially closer to security-based swap products.
In the U.S. regulatory system, security-based swaps will be subject to stricter restrictions, and there are special legal obstacles to selling them to ordinary retail investors. Once the court supports classifying U.S. equity perpetuals as security-based swaps, the existing product admission path will face fundamental challenges.
Behind the legal dispute is a real impact on commercial interests. The reason Cboe and Citadel Securities joined forces to block it is essentially to prevent U.S. equity perpetuals from undermining their business moats.
For Cboe, the options business is unquestionably its cash cow. In the third quarter of this year, its options business net revenue was close to $470 million, up 23% year over year, and its exchanges accounted for 30.5% of total U.S. options market trading volume. In addition to trading fees, market data, access services, and supporting clearing are also sources of revenue.
U.S. equity perpetuals, however, show a relatively high degree of substitution effect on options. For example, if an investor wants to go long Tesla with leverage, in the past they needed to buy call options and consider expiration dates, implied volatility, and strike price selection; in the future, they can directly gain price exposure by opening a long position through U.S. equity perpetuals, without having to manage rollovers and expirations.
For users who prefer short-term trading or leveraged bets, the needs of the two overlap. Once U.S. equity perpetuals gain volume, the first to be diverted will be retail trading volume in the options market.
For Citadel Securities, the impact falls on its market-making foundation. It holds about a 30% market-making share in the U.S. options market and handles 35% of U.S. retail equity trading volume. Its business model is built on order flow from traditional brokers and mature pricing and hedging systems.
If more and more retail investors trade U.S. equity perpetuals on crypto trading platforms, order flow will bypass traditional trading channels, and Citadel Securities' market-making revenue and pricing influence will both be weakened. Especially during after-hours and weekend periods, perpetual platforms can independently form quotes and executions, equivalent to opening a second pricing venue during the blank periods of the traditional market.
The deeper anxiety lies in regulatory asymmetry. Traditional stock and options exchanges have operated for years under strict SEC supervision and bear high compliance costs. If CEXs can launch products with similar economic functions merely through CFTC DCM qualification plus SEC registration, that is equivalent to entering the same market with lower compliance costs. Cboe stated bluntly in its comment letter to the SEC: incorrect product classification will leave room for "regulatory arbitrage" for new entrants.
In other words, what the giants oppose is not the U.S. equity perpetual product itself.
Cboe CEO Craig Donohue emphasized: if it were merely a business issue, Cboe could absolutely launch similar products on its own CFTC-regulated trading and clearing platform. Cboe already has complete futures trading and clearing infrastructure, and its Cboe Clear U.S. has DCO qualification; in October this year it also obtained temporary SEC registration approval for securities clearing. It is not incapable of entering the field; it simply does not want to compete under unfair rules.
Therefore, this lawsuit is more like a defensive counterattack: if successful, it will vacate the existing approval and force regulators to raise the threshold; if unsuccessful, it can still use judicial proceedings to lengthen the implementation cycle and leave the giants a window to position themselves. For traditional institutions, rather than killing the new category, pushing regulators to level the rules and return to the same starting line as the front-running players is the better solution.
Perpetual contracts have brought new trading mechanisms, and the crypto market has proven users' demand for trading perpetual contracts. But what ultimately determines whether U.S. equity perpetuals can establish a foothold in the market is still liquidity, trading costs, investor protection, and clear and stable regulatory rules. Whether product advantages can be transformed into competitiveness in the U.S. equity derivatives market also remains to be tested by time.
The CFTC has opened the door to the U.S. equity perpetual market, but obtaining trading qualification and truly winning the market have always been two different things.