




Author: Flow Brief by Alea Research
Compiled by: Deep Tide TechFlow
Deep Tide Introduction: Derive collected $360 million in options premiums in 9 months this year, capturing nearly 90% of the on-chain options market, with perpetual contracts contributing 40% of the fees. More critically, it has outperformed issuance with buybacks for 9 consecutive months, which is rare in the on-chain derivatives sector that relies on token issuance to survive: a 158% weekly token increase is not without reason. For those watching the DeFi options sector, this article explains clearly "why only it has survived."
Premiums rose 191.9% to $362.5 million, perpetual contracts contributed 40% of fees, and buybacks have been ahead of issuance for nine consecutive months
Derive collected $362.5 million in options premiums this year. This accounts for 87.4% of all on-chain options premiums, up 191.9% from $124.2 million for the full year of 2025. On September 17, DRV closed at a record high of $0.2877. By Saturday, the price reached $0.3857 (circulating market cap $385 million; fully diluted valuation $577 million), up 158% in a week. Coinbase spent $2.9 billion to acquire Deribit in May 2025.

Chart: Derive's share of on-chain options premiums, steadily above 80% since spring.
Derive has completely taken over on-chain options. This year, total on-chain options premiums were $414.9 million, of which it took $362.5 million, compared to only $124.2 million for the full year of 2025.
The room above it is Deribit. Derive trades $162.6 million in options per day, while all venues with public data combined traded $7.74 billion.
Perpetual contracts are not a supporting role. It earned $1.76 million of the $4.51 million in fees this year, accounting for 39.1%, and surpassed the options business in February.
Fees reach holders through buybacks. This venue retained $3.37 million of the $4.51 million in fees, using 35% of it to buy back DRV, having burned 16.6 million tokens this year, while staking rewards issued only 6.1 million tokens.
The options fee rate dropped from 2.94 cents per $100 traded to 1.27 cents, but the market revalued its earnings multiple from 22.5x to 48.7x.
The year Derive stopped sharing with others
In January, there were several on-chain options venues. Now there is only one, and the second place is too close to even be called competition.
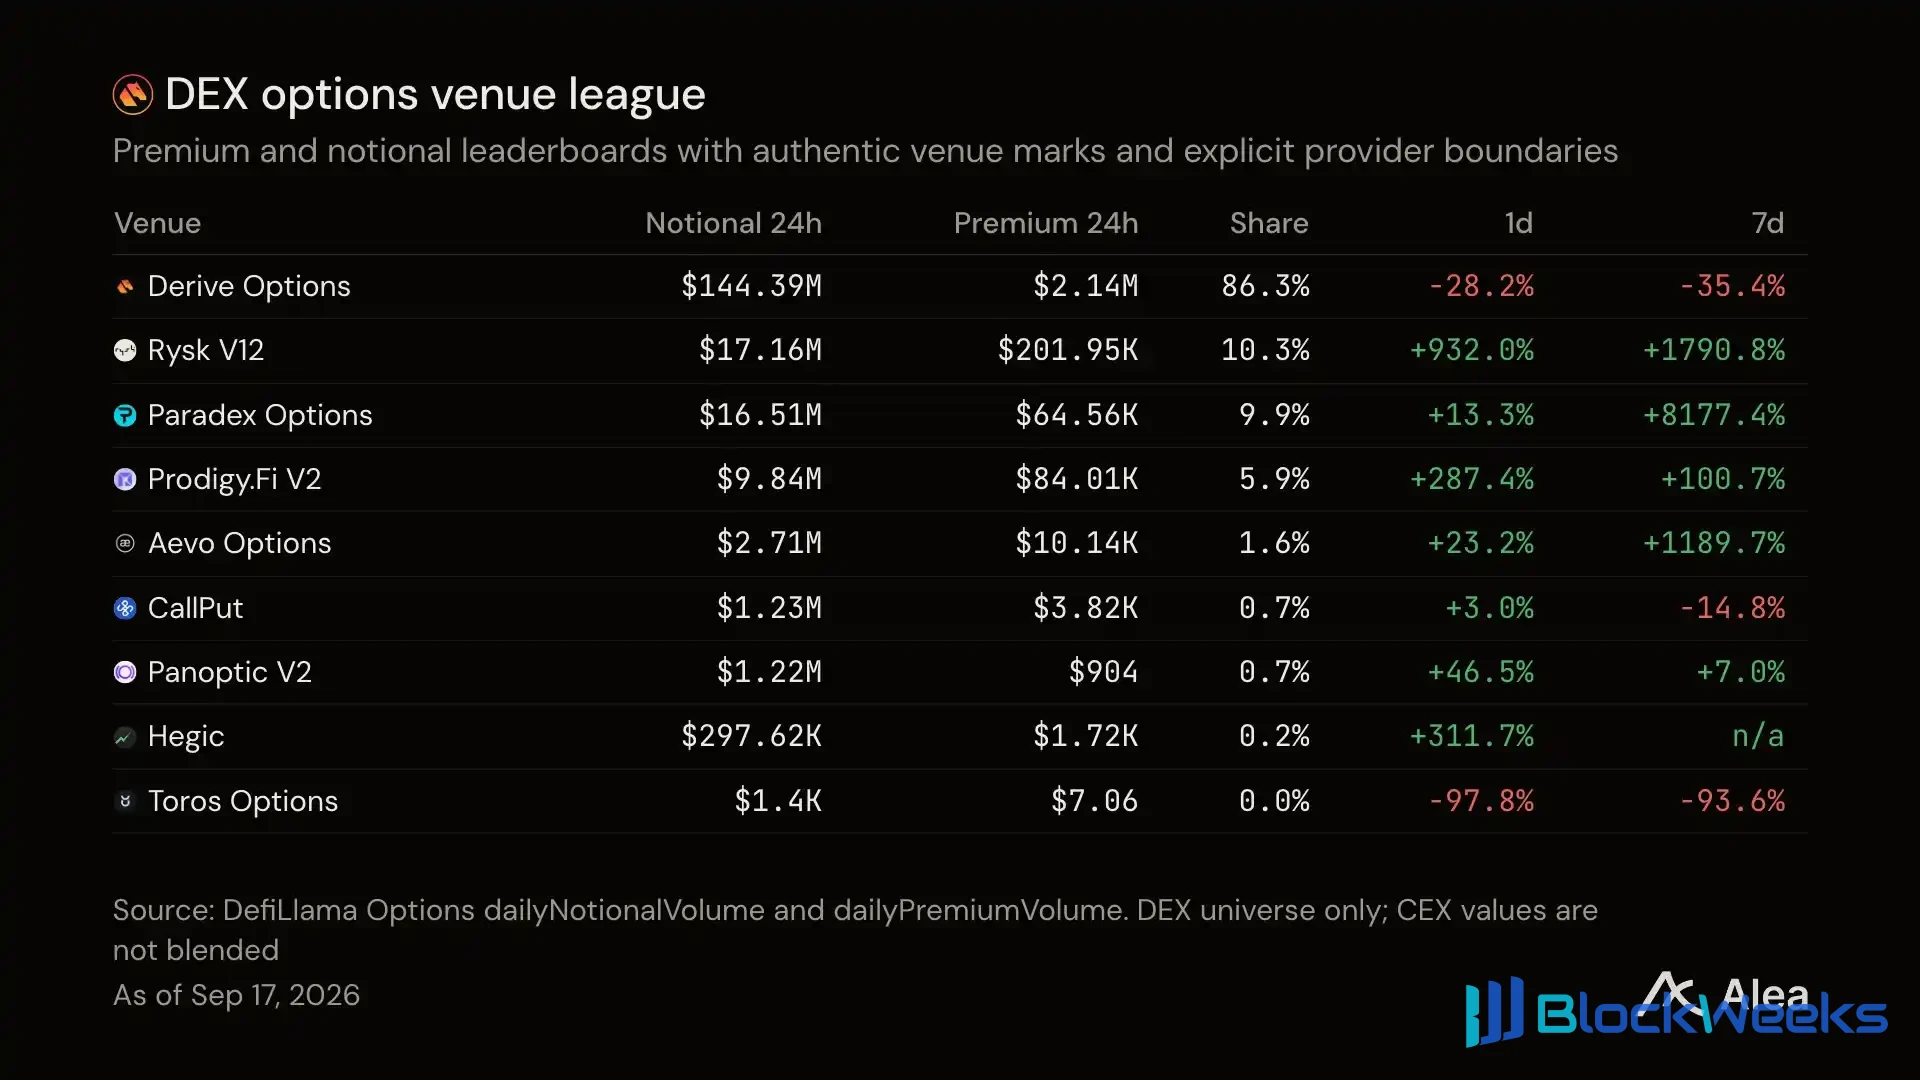
Chart: Each on-chain options venue ranked by premiums collected this year, in USD.
Deribit still trades $3.56 billion in options per day, while Derive only trades $162.6 million, a difference of nearly 22 times.
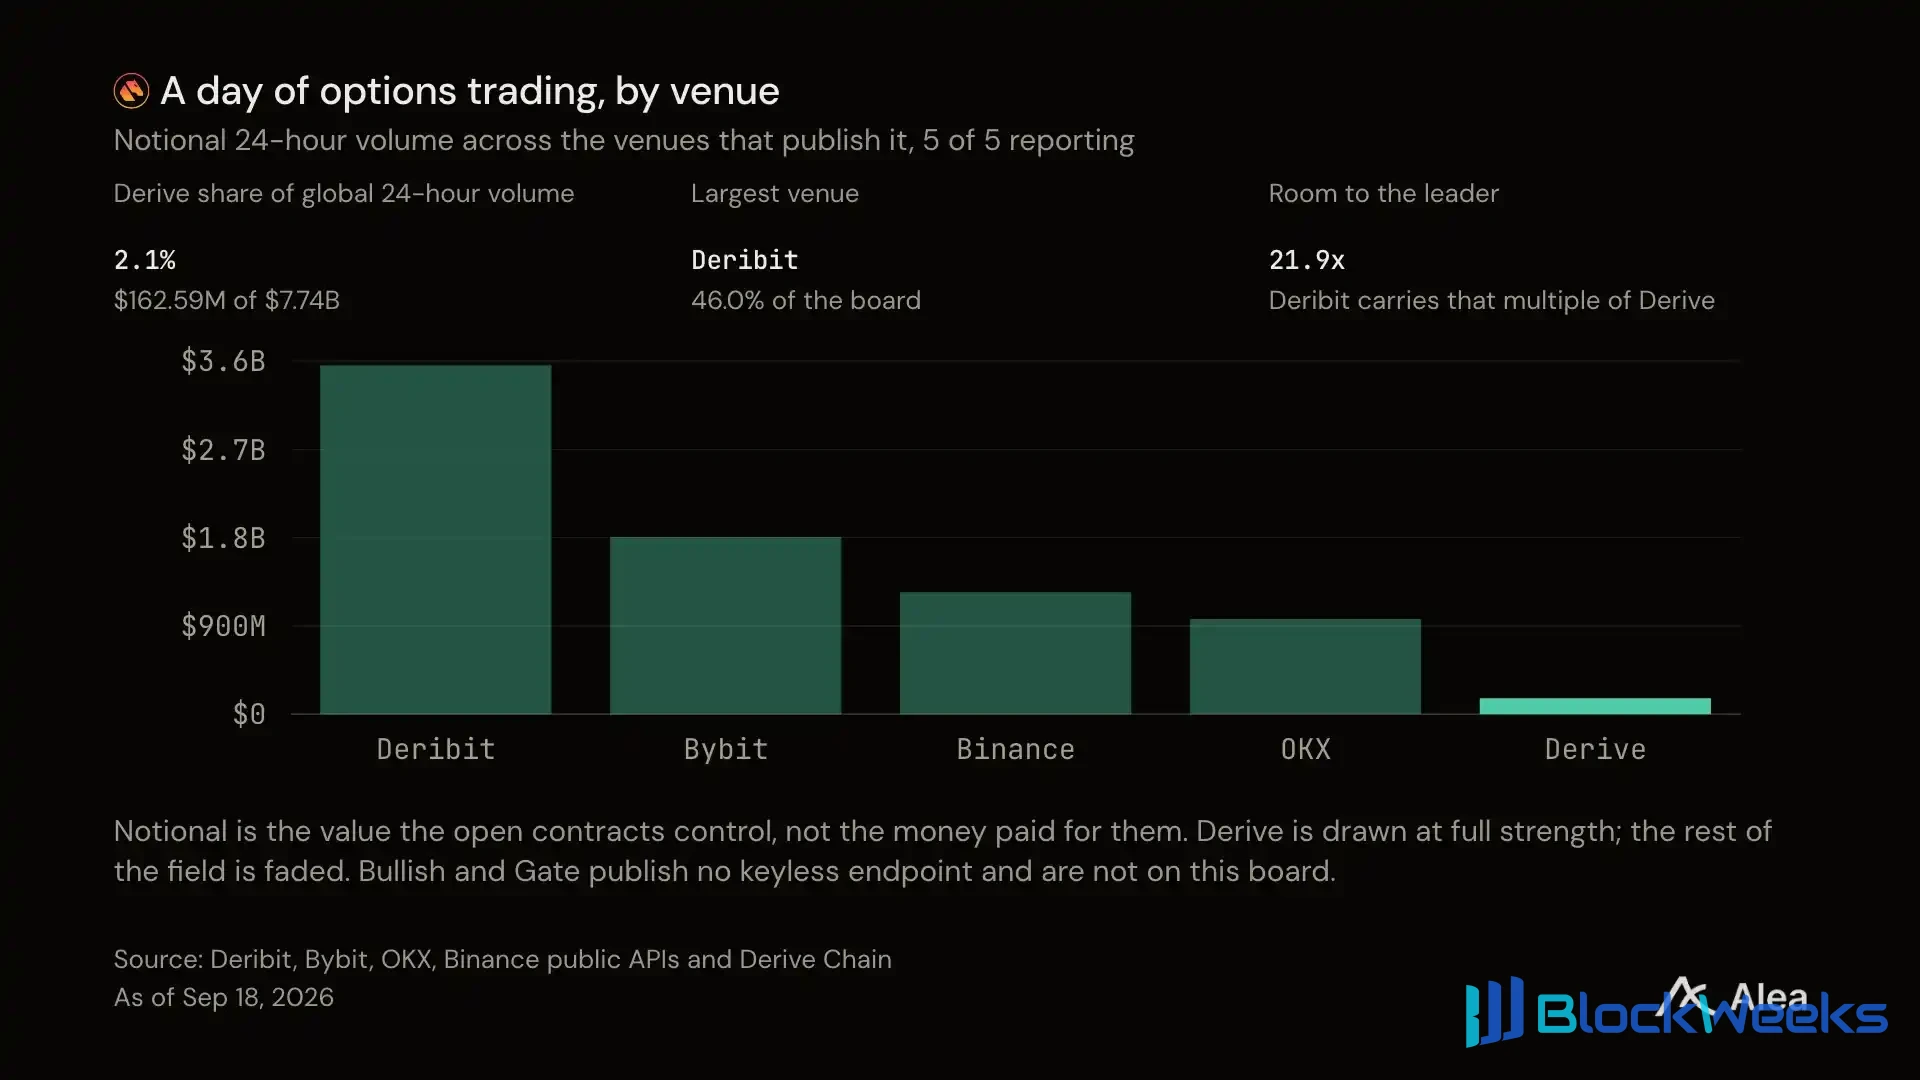
Chart: Daily options trading volume by venue, calculated as the USD value of assets controlled by contracts. Derive accounts for $162.6 million of the $7.74 billion total.
Open interest tells the same story. Derive holds $1.59 billion in positions out of a $50.22 billion pool, accounting for 3.2%. Deribit alone accounts for 78.8%.

Chart: Nominal open interest by venue, in USD.
Nine months did nearly three times last year
Premiums are the money paid by buyers, telling us whether a venue is being used and how much. Nominal trading volume rose from $5.38 billion to $12.46 billion.

Chart: Derive native options flow by month, in USD.
Buyers bought more exposure, and paid more for each dollar of exposure.
How much is a dollar of exposure worth
Premium divided by notional is the ratio of an option's price to the exposure it controls. The longer the tenor, the closer the strike is to the current price, and the greater the market's expected price volatility, the higher this ratio is.

Chart: Each bar is the percentage of a month's premium relative to the notional it controls.
All nine months of 2026 exceeded the 2025 median of 2.10%, and even the cheapest month was 2.23%. Over the same period, 30-day implied volatility fell by 7.0%. Buyers paid more for each dollar of exposure while volatility was falling.
This shows more options with longer tenors and strikes closer to the current price. Derive is being used like Deribit.
Comparing it with the quotes from that room above
Before switching venues, traders want just one number: how much the same risk costs in each of the two places.

Chart: At-the-money implied volatility by expiry, in percent, Derive versus Deribit.

Chart: The implied volatility difference between the two trading venues at the same strikes, in percentage points, covering all expiries quoted on September 17.
Quotes are only half of it. The other half is how much it costs to trade across the spread.

Chart: The cost of immediately executing at the best price at the same strikes on the two trading venues, in cents per $100.
Did sellers get paid for taking on risk
Implied volatility is what buyers pay for volatility. Realized volatility is the volatility that actually arrives. The gap between the two is the option seller's year: implied volatility fell by 7.0% over the year.

Chart: One-month implied volatility versus 30-day realized volatility, in percent.

Chart: The curve is the volatility range priced for each expiry, in USD.
What's in the Ledger
Open interest is the dollar value of positions still open. A place people just pass through to trade and a place people park their positions on look different.

Chart: Options open interest read from Derive Chain, in USD, full year.
Where Positions Sit
Expiry and strike price determine who is exposed to the next move.

Chart: Call and put open interest at each strike for selected expiries, in USD.

Chart: Gamma by strike, the dollar amount corresponding to each one percent price move. Gamma measures how quickly options exposure changes as price moves.
Who's Actually Trading It
Block trades and negotiated trades are how institutions build positions without moving the tape. The share of fees they contribute reveals who is on the other side.

Chart: Share of fees contributed by the largest accounts and negotiated trades, in percent.
The Other Ledger
Derive also runs perpetual contracts, a kind of price bet that never settles. That ledger did $5.2 billion in notional volume this year, contributing 39.1% of platform fees.

Chart: Daily perpetual notional volume and open interest at daily close, in USD; $5.2 billion traded this year, while open interest at the last close was $66.5 million.
The platform's daily volume is 0.30 times its open interest. Traders stay parked here rather than churning in and out.

Chart: Each active perpetual market ranked by 24-hour volume and its open interest: 15 markets, $47.49 million in volume, $66.12 million in open interest.
A total of 15 markets are listed. Two of them account for 82.3% of volume.
Funding rates are periodic payments between longs and shorts, and only move when one side's positions are crowded. On most of Derive's markets, it doesn't move at all.

Chart: Annualized funding rate for each market that deviates from the benchmark rate, in annualized percentage.
Five markets discovered their own rates: Bitcoin, Ethereum, Solana, Hyperliquid, and tokenized gold. Seven markets stayed at the platform's 10.95% benchmark annual rate for more than ninety percent of the time. Those five markets that discovered their rates also quieted down. The funding rates in these markets reached as high as 128.5% annualized before May, then 44.6%, while the deepest negative reading was halved from 173.0% to 92.2%.

Chart: Each launched perpetual market and the date of its first settled funding rate. As of September 17, 15 have launched, 12 have settled rates, and 3 have never settled.
The pace of trading instrument expansion has outpaced the pace of liquidity filling, especially in newer markets.
Where Passive Capital Goes
Vaults are where capital goes when it wants platform strategies but does not want to operate them itself. On Derive, vaults do only one of two things: sell options and keep the premium; or buy an asset, short it in the futures market, and earn the spread between the two prices.

Chart: 30-day change in vault assets, in USD, split into new capital and yield.
New capital and strategy performance are different reasons for vault growth, and only one of them shows that the strategy is working.

Chart: Yield of the basis vault, in annualized percentage, split into funding rate and cash interest.

Chart: Spread yield realized by the basis vault during the period, in USD.
How much depositors ultimately receive depends on the fees the vault charges and how much capacity remains.

Chart: Management fee, deposit cap, and account value for each vault, in percentage and USD.
Part of the platform's trading volume was bought, not earned.

Chart: DRV rewards paid per $100 of trading volume covered, in cents, over the past 30 days.
What the Platform Earned, and Who Got It
Fees are paid by traders. Revenue is the portion the platform keeps: $3.37 million this year.

Chart: Monthly fee split between the options ledger and the perpetuals ledger, in USD.
The options ledger earned $2.74 million, and the perpetuals ledger earned $1.76 million, i.e., 60.9% versus 39.1%. In February, the perpetuals ledger earned more than the options ledger.

Chart: Options fees as a share of notional contract value controlled, by month: 2.94 cents per $100 in January, 1.27 cents in September.
The options fee rate fell from 2.94 cents per $100 traded in January to 1.27 cents in September, a year-to-date decline of 56.7%. Trading volume rose over the same period, and total fees still grew.

Chart: The allocation of each dollar of fees among quote traders, the platform itself, and token holders.
Derive uses its fee share for buybacks rather than distributions. It burns supply instead of paying token holders.

Chart: Each bar is fee-driven buybacks minus DRV paid to stakers within a month, in millions of DRV.
All nine months were positive: 16.6 million DRV burned, 6.1 million issued. The DAO has burned a total of 27,645,461 DRV, 35% of fees. In April, it raised this ratio from 25% and cut weekly staking issuance from 250,000 DRV to 100,000, reducing the annualized issuance rate from 3.8% to 1.5%. The unstaking period was shortened from 28 days to 7 days.

Chart: Staked DRV and its share of circulating supply, in DRV and percent.
This year, circulating supply rose 17.1%, while the staking share fell from 39.1% to 28.6%.

Chart: Monthly fees and the share of revenue the platform retains, in USD.

Chart: Market cap divided by trailing 90-day annualized revenue, daily change.
This multiple moved more than any other figure this year. In January, the market paid 22.5 times the platform's annualized revenue; now it pays 48.7 times, a gain of 116.3%. The low was 14.3 times. Revenue continued to grow over the same months, meaning the repricing was not caused by a shrinking denominator.

Chart: The implied market cap corresponding to a given revenue scenario, multiplied by the multiple, in USD, and the change required from the most recent close to each scenario.
At 48.7x, the revenue corresponding to the price must continue to grow to support the valuation. The table above prices each assumption.
Established Arrangements
On September 14, a member submitted a proposal to deploy Derive V3. Matching and sequencer state transitions will run within a zero-knowledge virtual machine and settle to Ethereum. User funds will be held in Ethereum contracts. Once V2 positions, balances, and rewards are migrated to the V3 genesis state, Derive Chain will be gradually shut down. The stated goal is to reach L2Beat Stage 1, the tier at which users can exit without operator assistance.
On September 16, Derive stated that it had appointed Alex van Voorhees as Chief Legal and Compliance Officer. He previously came from FalconX, where he was responsible for derivatives legal affairs and served as interim compliance officer.
V3 settles on Ethereum, and the ZEC ledger currently runs through March 2027. The platform reported that of the 89,100 ETH call options that month, 96% had strike prices of $5,000 and $7,000, all held on Derive.